A fresh £53 million share purchase lifts the Heirs Group’s interest in Nigeria’s leading indigenous energy company above one-fifth, placing renewed attention on board independence, shareholder influence and related-party oversight.
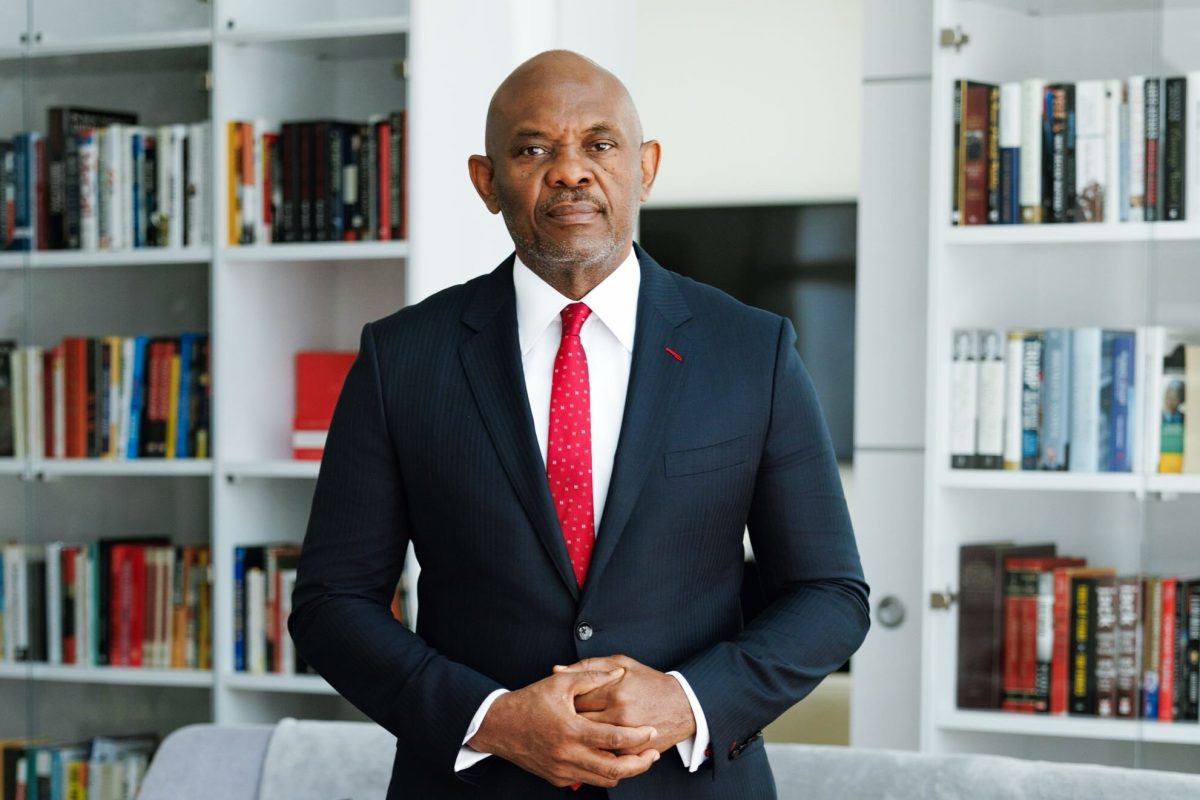
Tony Elumelu has strengthened his position in Seplat Energy Plc with another multimillion-pound share acquisition, taking the combined interest of companies under his control to 22.05 per cent. But beyond the growing investment, the transaction raises a more consequential question about the future governance of one of Nigeria’s most important energy businesses: how independently will its board operate when its incoming chairman is also the representative of one of its largest shareholders?
A regulatory disclosure published by Seplat Energy on 17 November 2026 confirmed that Heirs Energies Limited, a company controlled by Elumelu, purchased 5,888,341 ordinary shares on 16 November through the London Stock Exchange.
The shares were acquired at £9 each, giving the transaction a total consideration of £52,995,069, approximately £53 million.
Following the acquisition, Heirs Energies’ direct holding increased to 33,832,208 shares. Together with Heirs Holdings Limited, the entities controlled by Elumelu now hold 132,288,341 shares, equivalent to 22.05 per cent of Seplat’s 599,944,561 issued ordinary shares.
The latest purchase is not an isolated investment. It follows another substantial acquisition on 30 September, when Heirs Energies purchased six million shares at £8.87 each, spending £53.22 million.
That September transaction raised the combined Heirs Group holding to 126.4 million shares, representing 21.07 per cent of Seplat. The November acquisition subsequently increased that position to 22.05 per cent.
Together, the two purchases represent 11,888,341 additional shares acquired for approximately £106.22 million.
The distinction is important because the widely circulated account of the investment combines figures from the two transactions. The six million shares purchased at £8.87 belong to the September acquisition, while the 22.05 per cent ownership figure reflects the subsequent November purchase.
From a major investor to the company’s incoming chairman
The expansion of Elumelu’s investment is taking place against the backdrop of a planned leadership transition at Seplat.
His involvement began after the Heirs Group acquired the 20.07 per cent stake previously held by French oil and gas company Maurel & Prom on 31 December 2025.
The acquisition brought 120.4 million Seplat shares under the Heirs Group’s ownership and made Elumelu a major shareholder through the companies he controls.
He joined Seplat’s board as a non-executive director on 22 January 2026, following a proposal from the Heirs Group for board representation and for Elumelu to serve as its nominee.
On 9 June 2026, Seplat announced that its board had elected him to succeed Senator Udoma Udo Udoma as chairman.
Udoma is scheduled to retire on 31 December 2026, with Elumelu expected to assume the chairmanship on 1 January 2027.
In his response to the appointment, Elumelu said: “I firmly believe in the critical role indigenous resources play in the economic transformation of Nigeria and Africa.”
His statement reflects the wider ambition behind the Heirs Group’s investment in African energy assets. Yet his approaching appointment also makes the relationship between ownership and corporate oversight an important issue for investors.
The distinction between substantial influence and outright control must remain clear. A 22.05 per cent holding is significant, but it does not constitute majority ownership. The remaining 77.95 per cent of Seplat’s issued shares is outside the combined Heirs Group holding.
It would therefore be inaccurate to describe Elumelu as having acquired full ownership or automatic control of Seplat.
Nevertheless, a shareholder with more than one-fifth of a listed company’s equity, whose founder is also due to lead its board, occupies a particularly influential position.
The corporate governance question Seplat cannot ignore
The most important issue arising from the transaction may not be the size of the investment but the independence of the board that will oversee it.
Seplat is listed on both the Nigerian Exchange and the London Stock Exchange. Its 2025 integrated annual report identifies the UK Corporate Governance Code 2024 among the governance frameworks applicable to the company.
The Code’s Provision 9 states that a chairman should be independent on appointment when assessed against the circumstances outlined in Provision 10.
Those circumstances include representing a significant shareholder, which the Code identifies as a relationship likely to impair, or appear to impair, a non-executive director’s independence.
Provision 7 also requires boards to identify and manage conflicts of interest, including those arising from significant shareholdings, and to ensure that third-party influence does not compromise independent judgement.
This does not automatically establish a breach of the Code or make Elumelu’s appointment unlawful. The UK framework operates through a comply-or-explain approach, allowing companies to explain justified departures from particular provisions.
However, the question deserves a clear answer before the transition takes effect.
Seplat’s own conflict-of-interest policy sets additional standards for independent directors. These include restrictions on directly or indirectly holding more than 0.01 per cent of the company’s paid-up capital and on representing a shareholder capable of controlling or significantly influencing management.
The board therefore needs to explain how it has assessed the incoming chairman against the applicable independence standards, how any departure will be disclosed and what safeguards will protect independent decision-making.
A credible board must be capable of challenging the interests of even its largest investors.
The related-party relationships investors should understand
The governance question becomes more important when considered alongside the commercial relationships disclosed in Seplat’s nine-month financial statements.
The company’s report identifies Tony Elumelu as a director and shareholder of United Bank for Africa Plc.
UBA provides Seplat with banking services, financing and direct banking support. It is also one of the lenders under a ₦551.7 billion revolving credit facility, which remained undrawn as at 30 September 2026.
Seplat disclosed that it held balances totalling ₦119.7 billion with UBA at the end of the reporting period. The bank also provided a ₦1.3 billion customs bond for operational cargo clearance.
The financial statements further identify transactions with Transcorp Power Limited, an entity controlled by Elumelu.
Seplat reported gas sales transactions amounting to ₦3.1 billion and an amount due from Transcorp Power of ₦8.2 billion at the reporting date.
Another Elumelu-linked business, Transcorp Hotels Plc, provided hospitality services worth ₦1.1 billion during the period. Seplat reported an outstanding payable balance of ₦30.1 million.
Importantly, the company stated that “The terms of these transactions are at arm’s length.”
These disclosures do not establish wrongdoing, preferential treatment or financial misconduct. Nor does the existence of commercial relationships mean that the arrangements are inappropriate.
They do, however, make effective conflict management essential.
Seplat’s conflict-of-interest policy requires directors to disclose actual, perceived or potential conflicts. It also states that a director must not be present while a matter in which the director has an interest is being decided, or seek to influence the relevant discussions or negotiations.
Where the chairman is conflicted, the policy provides for the Senior Independent Non-Executive Director to exercise the chairman’s responsibilities in resolving the conflict, provided that the senior independent director is not also conflicted.
For investors, the practical test will be whether these protections are consistently applied, documented and disclosed.
Stronger earnings add to the attraction of Seplat
Elumelu’s growing exposure also comes as Seplat reports substantial improvements in its financial and operational performance.
For the nine months ended 30 September 2026, the company reported revenue of approximately US$2.764 billion, up 27 per cent from US$2.177 billion in the corresponding period of 2025.
Profit after tax increased by 174 per cent to US$260.2 million, compared with US$95.1 million a year earlier.
Average daily working-interest production rose by seven per cent to 144,999 barrels of oil equivalent per day.
But the earnings improvement should not be attributed entirely to increased production. Seplat’s average realised oil price climbed 34 per cent to US$96.19 per barrel from US$71.93 during the corresponding period.
Chief Executive Officer Effiong Okon acknowledged the contribution of stronger crude prices, stating: “We realised $100.4/bbl in the quarter.”
The company also reported US$556.9 million in cash at the end of September and net debt of US$234.9 million, a 65 per cent reduction from the end of 2025.
First commercial gas sales through the OB3 pipeline in September added another operational milestone to the company’s growing gas business.
However, Seplat’s updated guidance also identified higher unit operating costs of US$15.50–US$16.50 per barrel of oil equivalent, partly reflecting costs associated with the Yoho project. The company’s performance therefore still needs to be assessed against operating costs, project execution and the volatility of international oil prices.
The real test begins with the new board
There is a legitimate commercial argument for an influential shareholder to invest more deeply in a company in which he sees long-term potential.
Elumelu’s investment strengthens the presence of Nigerian capital in a strategic energy business and signals confidence in the value of indigenous ownership.
But ownership concentration also increases the responsibility placed on the board.
Seplat must demonstrate that its chairman can protect the interests of all shareholders, not simply those of the investment group with which he is associated.
That means transparent treatment of related-party transactions, effective independent directors, properly documented recusals and meaningful public explanations of how board independence is maintained.
The question facing investors is not whether Tony Elumelu has the financial capacity to increase his Seplat investment. The regulatory disclosures have established that.
It is whether Seplat can combine the influence of a major shareholder with the independence expected of a publicly listed energy company.
The answer will matter well beyond the boardroom. It will help determine whether international investors see Nigeria’s indigenous energy champions as companies capable of attracting substantial capital while maintaining the governance standards that make that capital sustainable.
Follow us on our broadcast channels today!
- WhatsApp: https://whatsapp.com/channel/0029VawZ8TbDDmFT1a1Syg46
- Telegram: https://t.me/atlanticpostchannel
- Facebook: https://www.messenger.com/channel/atlanticpostng
Join the debate; let’s know your opinion.