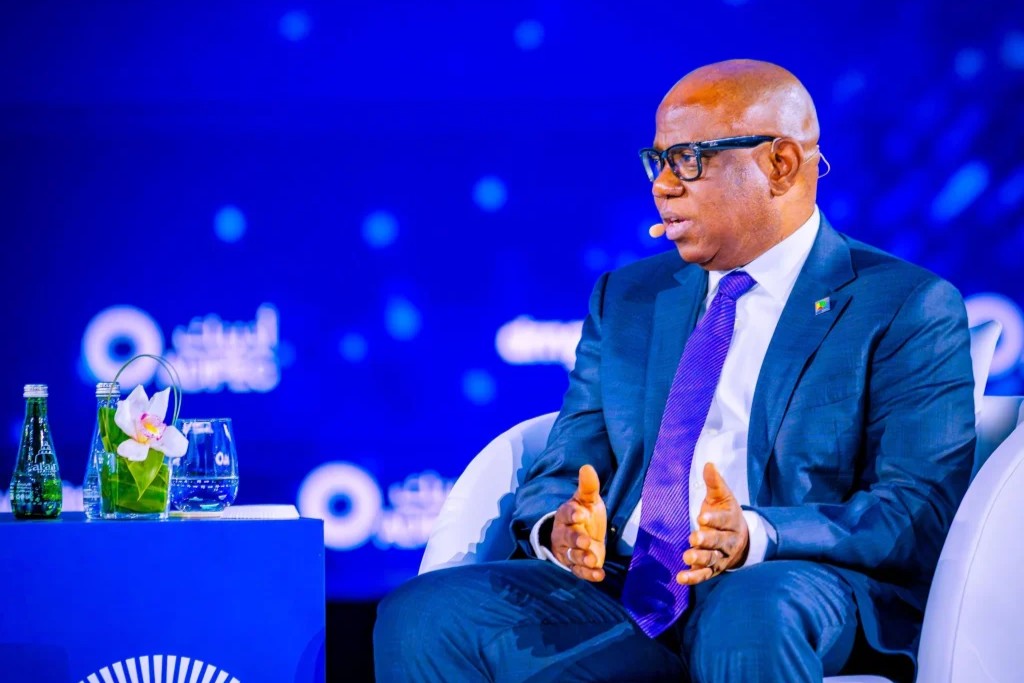
NNPC is considering selling up to 10% of its equity, with a possible London or New York listing. But the bigger test is whether ordinary Nigerians will gain genuine ownership, meaningful oversight and a clearer account of how the country’s oil wealth is managed.
The most important development is not simply that NNPC may become a publicly traded company. It is that Nigeria could be preparing to sell part of its most strategically important energy business while retaining overwhelming government control.
That raises a more consequential question than the size of the proposed share sale: will public investors acquire the power to hold NNPC accountable, or will they simply become minority shareholders in a company whose most important decisions remain firmly in government hands?
The Petroleum Industry Act 2021 provides a framework for public ownership, but requires government approval, National Economic Council endorsement, fair-market pricing and an open, transparent and competitive process for any transfer of government-held shares. It also requires NNPC Limited to retain 20% of its profits as earnings for business growth.
The investigation below examines the financial figures, the legal ownership structure, the lessons from Dangote’s share offering and the unresolved questions that should be answered before Nigerians are invited to invest.
NNPC’s proposed share sale is not privatisation
The Nigerian National Petroleum Company Limited is considering a landmark opening of its ownership to private investors. But the proposed transaction is deliberately limited.
Speaking to Reuters on 3 November 2026 at the Abu Dhabi International Petroleum Exhibition and Conference (ADIPEC), Group Chief Executive Officer Bashir Bayo Ojulari said NNPC was likely to float between 5% and 10% of its equity through an initial public offering.
The Nigerian market would be the primary destination. A secondary listing in London or New York could follow.
The company is also considering separate listings of some subsidiaries, potentially following the approach adopted by the United Arab Emirates’ Abu Dhabi National Oil Company (ADNOC).
The preparations are expected to occupy at least the whole of 2027. Ojulari said the main objective was to improve transparency and corporate governance, with raising capital a secondary consideration.
The distinction is important.
An offering of 5% to 10% does not amount to the privatisation of NNPC. Assuming the government sells existing shares rather than issuing new equity, it would retain between 90% and 95% ownership.
The Federal Government would therefore remain the dominant shareholder, with the ability to retain decisive influence over the company’s strategic direction.
Investors would acquire an economic interest in NNPC, but the extent of their influence over management, board appointments and major decisions would depend on the rights attached to their shares and the governance structure established before listing.
This is where Nigeria’s proposed transaction becomes more complicated than an ordinary public offering.
The country wants the credibility of private-sector scrutiny without surrendering control of an institution that sits at the centre of its energy security, petroleum resources and national finances.
That balance is possible. But it requires more than placing shares on a stock exchange.
What the Petroleum Industry Act actually permits
The legal foundation for the proposed offering already exists.
The Petroleum Industry Act 2021 transformed the former Nigerian National Petroleum Corporation into Nigerian National Petroleum Company Limited, with the commercial transition taking effect in July 2022.
Under Section 53, the Federal Government initially holds all shares through the Ministry of Finance Incorporated and the Ministry of Petroleum Incorporated, with each holding an equal portion on behalf of the Federation.
The legislation also establishes safeguards for any disposal of government-owned shares.
Section 53(5) requires government approval and endorsement by the National Economic Council on behalf of the Federation before government-held shares can be transferred.
Section 53(6) further requires sales to take place at fair market value through an open, transparent and competitive bidding process. Shares must be transferred in equal proportion from the two government holding entities. LawGlobal Hub
These provisions have major implications.
The Federal Government cannot simply decide privately that a particular investor should acquire a sizeable portion of the national oil company’s equity.
Any disposal must satisfy the statutory conditions.
The Act also requires NNPC and its subsidiaries to operate commercially, profitably and efficiently without recourse to government funds. It requires the company to declare dividends to shareholders and retain 20% of profits as retained earnings to finance business growth.
This is an important distinction between the old NNPC and the company Nigeria is now attempting to prepare for the capital market.
The national oil company is no longer supposed to function as an unlimited government spending instrument.
Its commercial performance must be measurable. Its obligations must be identifiable. Its financial reporting must withstand scrutiny.
An IPO would expose these responsibilities to a wider group of investors.
But the legislation establishes the framework, not the guarantee that the framework will work in practice.
The ₦7.2 trillion profit raises another investment question
NNPC is approaching the proposed offering with an impressive headline profit.
Its audited 2025 financial results, published on 29 September 2026, show profit after tax of ₦7.18 trillion, approximately 33% higher than the ₦5.41 trillion recorded in 2024.
The company also announced a dividend of ₦5.8 trillion.
But there is a significant qualification.
Revenue declined by approximately 23.4%, falling from ₦45.08 trillion in 2024 to ₦34.52 trillion in 2025.
Gross profit also fell from ₦11.71 trillion to ₦9.37 trillion.
NNPC attributed the revenue decline principally to lower crude oil prices and reduced petroleum product volumes following market deregulation in 2024.
NNPC’S FINANCIAL PERFORMANCE
| Financial measure | 2024 | 2025 |
|---|---|---|
| Revenue | ₦45.08tn | ₦34.52tn |
| Profit after tax | ₦5.41tn | ₦7.18tn |
| Gross profit | ₦11.71tn | ₦9.37tn |
| Other income | ₦3.39tn | ₦8.42tn |
| Sundry income | ₦2.53tn | ₦7.10tn |
Source: NNPC’s 2025 audited financial statements, as reviewed by Nairametrics. Figures rounded.
The numbers expose a question that should matter to any prospective shareholder.
How did NNPC increase its after-tax profit by almost a third while its revenue and gross profit moved in the opposite direction?
Part of the explanation lies in the company’s other income.
The ₦7.1 trillion sundry income question
NNPC recorded ₦8.42 trillion in other income in 2025, compared with ₦3.39 trillion in 2024.
Within that amount, sundry income rose from ₦2.53 trillion to ₦7.10 trillion.
The figure is equivalent to approximately 99% of the company’s reported after-tax profit. This does not mean sundry income alone generated 99% of the profit. It is a comparison of the size of two different accounting measures.
NNPC’s financial disclosures identify several sources of sundry income, including Trans-Forcados pipeline income, crude processing fees, miscellaneous receipts from joint-venture operators and a write-back of a previously recognised provision relating to the Amenam-Kpono stock overlift claim.
The problem for outside investors is that the financial report does not provide a separate monetary breakdown for each of these four components.
Consequently, an investor cannot readily establish how much of the ₦7.10 trillion came from recurring business activities and how much arose from individual adjustments or less predictable income streams.
The company also recorded ₦1.99 trillion in net other losses, predominantly associated with realised and unrealised foreign-exchange losses. Nairametrics
This is not evidence of financial misconduct.
It is, however, precisely the kind of disclosure issue that becomes important when a company seeks a public valuation.
Investors need to know whether earnings can be repeated, what drives them and how much depends on exceptional or non-core transactions.
A profitable company is not automatically a predictable investment.
The proposed IPO should therefore be accompanied by financial disclosures that distinguish recurring operating earnings from exceptional receipts, accounting adjustments and foreign-exchange movements.
The preliminary revenue figures need proper reconciliation
Another issue illustrates why financial reporting will be central to investor confidence.
NNPC’s December 2025 monthly report summary initially presented provisional full-year revenue of approximately ₦60.52 trillion and profit after tax of ₦5.76 trillion.
The report expressly described the figures as provisional and subject to reconciliation. It also stated that its revenue reflected aggregate group-wide earnings, including intercompany transactions.
The audited financial statements subsequently reported revenue of ₦34.52 trillion and profit after tax of approximately ₦7.18 trillion. Punch Newspapers+1
These figures should not automatically be treated as contradictory. The provisional revenue measure included intercompany transactions, whereas the audited reporting provides a different basis for assessing the financial performance.
Nevertheless, the figures demonstrate why an IPO prospectus must explain the accounting perimeter, consolidation adjustments and methodology behind the numbers investors are being asked to value.
The national oil company cannot expect investors to interpret substantial differences in financial reporting without a clear reconciliation.
Future oil production is already carrying financial obligations
There is another issue that prospective shareholders will need to understand.
NNPC’s audited 2025 financial statements show that its forward-sale obligations increased to approximately ₦8.25 trillion, from ₦6.21 trillion in 2024.
These arrangements involve receiving money in advance against oil and gas products to be delivered in the future.
The obligations increased by about 33% during the year and accounted for approximately 95% of the company’s total contract liabilities, according to Nairametrics’ review of the accounts.
NNPC also paid approximately ₦847.6 billion in interest on contract liabilities, compared with ₦272 billion in 2024.
Such financing arrangements are not inherently improper. They can provide liquidity for operations and investment.
But they create a financial responsibility that prospective shareholders cannot ignore.
Oil and gas deliveries used to settle previous financing arrangements cannot simply be treated as entirely fresh revenue available for new projects or dividends.
The company’s future cash flows must be assessed alongside these commitments.
The published disclosures do not establish that most of Nigeria’s future production has been committed or that the arrangements eliminate government revenue. That distinction is important.
Nevertheless, an investor purchasing NNPC shares should have a clear understanding of the outstanding commitments, their maturity dates, financing costs, repayment terms and implications for future cash generation.
The question is not simply how much oil NNPC produces.
It is how much of the resulting income remains available after contractual commitments and operating costs have been met.
The 2026 performance will also shape the valuation
The company’s 2025 results should not be considered in isolation.
NNPC recorded ₦2.28 trillion in profit after tax during the first half of 2026, a decline of approximately 35.4% from the ₦3.53 trillion recorded in the corresponding period of 2025.
There has been some subsequent improvement.
According to its September 2026 monthly report, released on 3 November, NNPC recorded revenue of ₦4.61 trillion and profit after tax of ₦509 billion during the month.
Crude oil and condensate production stood at 1.70 million barrels per day, while natural gas output reached 7,789 million standard cubic feet per day.
The company also reported ₦11.14 trillion in statutory payments between January and September 2026.
These figures show a substantial operating business, but also one exposed to fluctuations in production, prices, operational reliability and financing costs.
NNPC has set a target of two million barrels of crude oil production per day by 2027 and three million barrels per day by 2030.
It is also seeking to mobilise $60 billion in investment across the upstream, midstream and downstream sectors by 2030. NNPC
These ambitions may strengthen the investment case.
But prospective investors will want to know how much capital is required to deliver them, which projects are commercially viable, what returns are expected and whether existing financial obligations could constrain investment spending.
Dangote’s IPO has created an opportunity, not a guarantee
The proposed NNPC listing comes immediately after a remarkable demonstration of domestic investor appetite.
The Dangote Petroleum Refinery’s public offer, which closed on 27 October 2026, attracted orders worth approximately ₦6.4 trillion, equivalent to $4.78 billion, against a targeted offering of about $1.6 billion.
That represented almost three times the targeted offer.
Reuters reported that more than two million investors had subscribed through digital channels, with applications coming from investors across all 54 African countries and 120 countries worldwide.
The offering was expected to attract further demand through a possible greenshoe option, which could increase its size to approximately $2.1 billion.
Importantly, the ₦6.4 trillion represented orders, not the final amount raised or the value of shares ultimately allotted. Reuters
The demand is significant.
It suggests that Nigerian investors, including ordinary retail participants, are willing to consider sizeable investments in domestic energy businesses when the opportunity is accessible and commercially attractive.
For NNPC, this could provide a valuable foundation.
But the two businesses are not identical.
Dangote’s offering is centred on a major industrial refinery with a defined commercial asset and expansion strategy.
NNPC is a much broader energy conglomerate with interests across crude oil production, natural gas, pipelines, petroleum products, subsidiaries and strategic national energy infrastructure.
Its valuation will therefore require a more complicated assessment.
Investors will need to understand the profitability of individual businesses, the quality of underlying assets, liabilities across subsidiaries and the extent to which government policy obligations affect commercial returns.
Dangote’s subscription success cannot substitute for that work.
ADNOC offers a useful model, but Nigeria must understand the difference
Ojulari’s reference to ADNOC is particularly relevant.
The UAE’s state-owned energy group has brought several subsidiaries to the public market while retaining substantial state ownership.
ADNOC Gas, for example, completed a 5% IPO on the Abu Dhabi Securities Exchange in March 2023, raising $2.5 billion.
A subsequent share placement in February 2025 increased its free float to 9%.
ADNOC remains the parent organisation, retaining its position as the majority owner of the listed subsidiary.
The model demonstrates that a state-owned energy company can access public capital without giving up control of its wider business.
It also offers a potentially important strategy for NNPC.
Rather than relying exclusively on a single offering of the parent company, individual subsidiaries could be prepared for public investment where their financial records, assets and commercial operations are sufficiently established.
This could allow investors to assess specific businesses rather than attempting to value the entire national oil company through a single share price.
However, a subsidiary IPO is only attractive when the subsidiary has clearly defined assets, liabilities, management responsibilities and reliable financial statements.
The lessons from ADNOC are therefore about transparent asset structures and disciplined capital-market preparation, not simply copying the percentage of shares offered.
The unresolved question: Who will hold NNPC accountable?
Ojulari has acknowledged that the company is still working through its preparation requirements.
On 14 October 2026, he told Bloomberg:
“We’ve done the baseline assessment.”
He explained that advisers had identified weaknesses requiring attention, including changes to reporting structures and corporate governance frameworks. TheCable
The statement is significant.
A company preparing for an IPO should not still be resolving fundamental questions about its reporting architecture and governance arrangements shortly before issuing shares.
These preparations must establish an institutional structure capable of surviving changes in government and management.
The CEO had already explained the ownership decision on 29 September 2026, saying:
“We don’t have a date, but we are working hard to make sure we are ready as soon as we can. The decision to take an IPO is not ours. It’s the shareholders that will take that decision ultimately on behalf of the country.”
That position reflects the present legal structure.
The Federal Government remains NNPC’s shareholder, and management cannot independently decide to dispose of national equity.
Yet it also raises a fundamental governance question.
If the government remains overwhelmingly in control after the offering, how will minority investors ensure that commercial decisions are not displaced by political considerations?
This is particularly important in an industry where national energy security, domestic petroleum supply, infrastructure investment and government revenue can sometimes compete with shareholder returns.
A listed NNPC should be able to explain which activities are commercial, which are undertaken for national policy reasons and who bears the cost when those objectives conflict.
The distinction should not be left to political interpretation.
Five disclosures Nigerians should demand before the IPO
Before the Securities and Exchange Commission and the Nigerian Exchange approve an offering, the market should expect a comprehensive disclosure framework.
Five areas deserve particular attention.
1. An independently defensible valuation. The government should publish the valuation methodology, the underlying assets, liabilities, major assumptions and risks. The sale must comply with the Petroleum Industry Act’s fair-market-value requirement.
2. A full picture of subsidiary finances. Investors should be able to examine the financial performance of major business units and understand how their accounts are consolidated into the parent company’s financial statements.
3. Complete disclosure of forward-sale obligations. The company should explain its crude-backed financing, contractual commitments, interest expenses and their impact on future cash flows.
4. Independent corporate governance. Minority shareholders need meaningful protection, transparent board procedures, reliable audit oversight and clear rules governing transactions involving government-related entities and other interested parties.
5. A clear dividend and reinvestment policy. Investors must understand what proportion of earnings will be distributed, retained or committed to major capital projects, particularly under the PIA’s 20% retained-earnings requirement.
Without these safeguards, an IPO could increase the number of NNPC shareholders without fundamentally improving accountability.
Nigeria is selling more than shares
NNPC’s proposed flotation could become one of the most consequential developments in Nigeria’s capital market.
It could introduce millions of Nigerians to direct ownership of a company whose performance affects the country’s energy industry, government finances and wider economy.
It could also bring international investors into a market that has struggled to attract sufficient long-term capital for its oil and gas infrastructure.
But the transaction should not be judged by how much money it attracts or whether NNPC secures a prestigious listing in London or New York.
The more important measure is whether the company becomes more transparent after private investors acquire a stake.
Ojulari has offered a useful standard for measuring progress. Speaking at ADIPEC on 3 November, he said:
“Our track record will be judged by what is done and not by what is said.”
That standard should apply to the IPO itself.
NNPC must demonstrate that its accounts can be understood, its subsidiaries independently assessed, its financial commitments properly disclosed and its management held accountable.
For Nigeria, the proposed sale is an opportunity to change the relationship between citizens and their national energy resources.
But owning 5% or 10% of NNPC will mean little if shareholders cannot see how the company makes its money, where the money goes and who makes the decisions.
The real test of the NNPC IPO is not whether Nigerians can buy shares in their national oil company. It is whether those shares will finally give them a credible way to see, question and hold the institution accountable.
Follow us on our broadcast channels today!
- WhatsApp: https://whatsapp.com/channel/0029VawZ8TbDDmFT1a1Syg46
- Telegram: https://t.me/atlanticpostchannel
- Facebook: https://www.messenger.com/channel/atlanticpostng
Join the debate; let’s know your opinion.