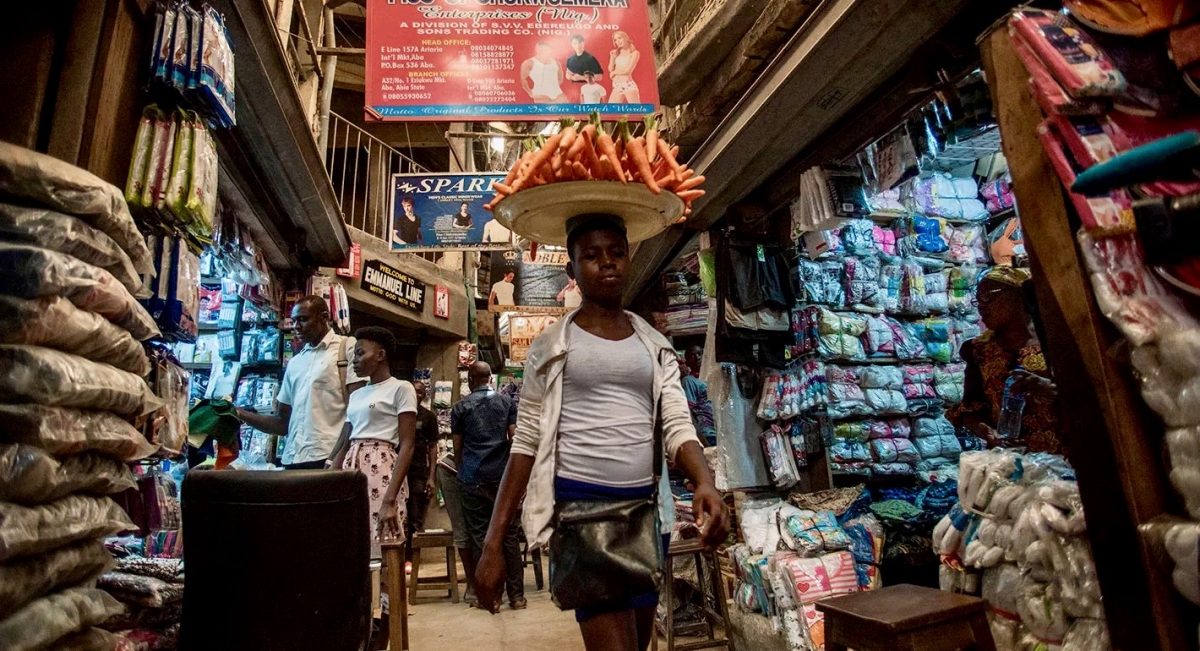
A business can have customers, make daily sales and even attract attention on social media, yet still be heading towards closure. For many Nigerian entrepreneurs, the problem is not a lack of effort. It is the inability to turn commercial activity into a sustainable, profitable business.
Across Nigeria, small businesses face rising operating costs, unreliable electricity, expensive credit, changing consumer behaviour and an increasingly demanding regulatory environment. Some struggle to survive their first year. Others remain in business for years without generating enough profit to expand, employ more people or withstand an unexpected financial shock.
The pressure is real. The Central Bank of Nigeria’s September 2026 Business Expectations Survey identified multiple taxation, insecurity and high interest rates as the three leading constraints on business activity. They recorded constraint indices of 67.1, 66.2 and 64.3 points respectively. These are index scores, not percentages of businesses affected.
Yet external difficulties do not explain every business failure. Many enterprises also suffer from weak financial management, poor customer research, inadequate capital, unrealistic pricing and an excessive dependence on their owners.
Understanding these weaknesses is important because starting a business is only the first challenge. Building one that can survive Nigeria’s difficult economic conditions is the real test.
Here are five reasons Nigerian small businesses fail and practical steps entrepreneurs can take to avoid them.
1. They Start Businesses Without Understanding Their Customers
One of the most common mistakes Nigerian entrepreneurs make is confusing an attractive business idea with a commercially viable opportunity.
Someone notices that a particular product is selling well in Lagos and decides to introduce it in Asaba, Port Harcourt or Abuja. Another entrepreneur sees a successful restaurant on social media and opens a similar establishment without investigating the spending habits, preferences and purchasing power of customers in the intended location.
The problem is that a successful business elsewhere does not automatically translate into a profitable opportunity in another market.
Some business owners invest heavily in premises, equipment, products and branding before establishing whether enough people are willing and able to pay for what they intend to sell.
Others assume that posting products regularly on Facebook, Instagram, WhatsApp or TikTok will automatically generate customers.
Visibility is important, but visibility is not the same as demand.
A survey of 180 Nigerian MSME operators conducted by Miva Open University between September and November 2025 found that more than 83 per cent of respondents reported declining sales. Approximately 81 per cent also identified difficulties reaching customers beyond their immediate markets. The survey is indicative rather than a nationally representative estimate, but its findings highlight the importance of demand and market access.
How to avoid this mistake
Before investing substantial money, entrepreneurs should establish whether a genuine market exists.
Start by identifying a specific customer group. Find out what people buy, how frequently they buy it, what they currently pay and what problems they want solved.
Speak directly to potential customers. Ask questions about their preferences and purchasing behaviour rather than simply asking whether they like a proposed business idea.
Test the market on a small scale. An entrepreneur planning to open a bakery, for example, could begin with online orders, home deliveries or supply arrangements with existing retailers before committing to expensive premises.
Businesses should also identify their competitive advantage. It might be better customer service, more convenient delivery, superior quality, competitive pricing or a product that addresses an overlooked need.
The most important question is not whether people like the idea.
It is whether they will consistently pay for it.
2. They Confuse Sales Revenue With Profit and Ignore Cash Flow
A business can record impressive daily sales and still struggle to pay its rent, suppliers, employees and electricity bills.
This happens when owners focus on the money entering the business without properly calculating how much remains after expenses.
Consider a small retail business that generates ₦500,000 in monthly sales. The owner may regard this as a successful month. Yet the business could have spent ₦180,000 purchasing stock, ₦100,000 on rent and utilities, ₦70,000 on transportation, ₦60,000 on salaries and another ₦50,000 on other operating expenses.
The actual surplus would be just ₦40,000, before accounting for other obligations or unexpected costs.
The owner has made ₦500,000 in sales, but that is not the same as earning ₦500,000 in profit.
The situation becomes worse when business owners allow customers to purchase on credit, accumulate unsold inventory, withdraw money for personal expenses or fail to monitor outstanding payments.
A profitable business on paper can collapse when it runs out of cash.
Poor record-keeping also creates another problem: businesses struggle to demonstrate their financial performance when seeking loans, investment or commercial partnerships.
BusinessDay’s reporting on the 2025 World Bank Enterprise Survey found that although 94.8 per cent of Nigerian SMEs surveyed had bank accounts, only 20.2 per cent had access to bank loans. The report also noted that 42 per cent were partially credit-constrained.
Without reliable financial records, lenders have less evidence with which to assess a business’s revenue, expenses, profitability and ability to repay.
How to avoid this mistake
Every small business should maintain a basic financial management system, regardless of its size.
At a minimum, entrepreneurs should:
- Record every sale and business expense.
- Separate personal and business finances.
- Reconcile bank transactions and cash balances regularly.
- Track stock purchases, outstanding customer payments and supplier debts.
- Prepare a monthly profit and loss statement.
- Monitor cash flow and plan for upcoming expenses.
Free or affordable digital accounting tools and properly maintained spreadsheets can help smaller enterprises establish these systems.
Entrepreneurs should also prepare a cash flow forecast showing the money expected to enter and leave the business over the next 30 to 90 days.
The International Growth Centre’s Nigerian pilot research found that combining digital record-keeping tools with personalised business support increased the probability that small firms would take their first steps towards adopting digital records by 95 per cent compared with providing basic information alone.
Good financial records are not administrative decoration. They are an early-warning system that helps owners identify problems before they become serious.
3. They Start Underfunded or Borrow Money Without a Repayment Strategy
Many Nigerian entrepreneurs underestimate how much money they need to establish and sustain a business.
They calculate the cost of purchasing equipment, securing a shop or buying their first stock but overlook the working capital required to operate while waiting for sales to become consistent.
A restaurant, for example, needs more than cooking equipment and food ingredients. It must also pay rent, electricity, staff salaries, transportation, marketing and other expenses, even when customer traffic is unpredictable.
The same principle applies to retail outlets, manufacturing businesses, agricultural ventures and service companies.
When initial capital is inadequate, owners often turn to expensive borrowing to cover routine expenses. Some use personal loans or short-term digital credit to finance business activities that will not generate returns quickly enough to support repayment.
The debt then becomes an additional burden.
Access to affordable financing remains a serious issue. In December 2025, the World Bank approved a $500 million financing package for Nigeria’s Fostering Inclusive Finance for MSMEs project, to be implemented through the Development Bank of Nigeria and its credit-guarantee subsidiary.
The World Bank noted that fewer than one in 20 Nigerian MSMEs had access to bank credit, with high borrowing costs, short loan tenures and collateral requirements excluding many otherwise viable businesses.
This illustrates an important distinction: having a business idea is not the same as having a financing structure capable of supporting it.
How to avoid this mistake
Entrepreneurs should prepare a realistic financial plan before launching.
Calculate the initial investment, operating expenses, expected revenue and the time required for the business to generate sufficient cash.
Set aside working capital to cover essential expenses during periods of weak sales. The amount required will depend on the business model, but owners should avoid committing all their available funds to equipment, inventory or decoration.
Borrowing should be based on a clear repayment plan.
Before accepting a loan, consider:
- The effective interest rate and additional charges.
- The repayment period and frequency.
- Expected monthly cash flow.
- What happens if sales fall below projections.
- Whether the borrowed money will finance an income-generating activity.
Where possible, match long-term borrowing to long-term investments rather than using short-term loans to finance assets that will take years to generate returns.
Entrepreneurs should also investigate legitimate financing opportunities through development finance institutions and established lenders. They should verify eligibility, repayment conditions and application procedures directly, rather than paying unverified agents promising guaranteed loans.
Capital is important, but how it is deployed can determine whether a business survives.
4. They Underprice Their Products and Underestimate Operating Costs
A product can sell quickly and still make its owner poorer.
This is particularly dangerous in Nigeria, where the cost of running a business can change considerably over a short period.
Electricity, fuel, transportation, rent, raw materials, internet services, salaries and security expenses all contribute to the cost of operating an enterprise.
For businesses that depend on imported materials or equipment, exchange-rate movements can create additional uncertainty.
A business owner who calculates product prices using last month’s costs may discover that replacing the same stock now requires considerably more money.
Some entrepreneurs respond by increasing sales volumes or offering discounts, believing that higher turnover will compensate for reduced margins. In reality, they may be selling more products while making less money on each transaction.
Miva Open University’s 2025 MSME survey found that more than 86 per cent of its 180 respondents identified inflation and rising operating costs as their biggest challenge. High energy and transportation expenses were among the pressures reducing profit margins.
The CBN’s latest September 2026 findings also show that multiple taxation remains a leading business concern.
These pressures are not entirely within the control of individual entrepreneurs. Nevertheless, businesses can improve how they calculate costs, price products and manage resources.
How to avoid this mistake
Every entrepreneur should understand the full cost of delivering a product or service.
A retail business should account for purchase prices, transportation, storage, damaged stock, packaging, payment charges and other relevant expenses.
A manufacturer should consider raw materials, electricity, labour, maintenance, wastage, delivery and production overheads.
A service business should account for staff time, software, internet, marketing, professional fees and other costs required to serve customers.
Pricing should be based on these costs, the value delivered and what the target market can realistically afford.
Business owners should also calculate their break-even point.
This is the level of sales required to cover the business’s costs without making a profit or loss.
For example, if a business has monthly fixed costs of ₦300,000 and generates a contribution margin of 30 per cent, it must achieve approximately ₦1 million in monthly sales to break even.
Understanding this figure allows entrepreneurs to establish realistic sales targets.
Other useful measures include negotiating better supplier terms, reducing unnecessary inventory, preventing wastage, reviewing delivery arrangements and exploring shared services where appropriate.
Most importantly, entrepreneurs should review their prices whenever significant costs change.
Being competitive does not mean being the cheapest business in the market. It means offering customers value while retaining enough profit to sustain operations.
5. They Depend on the Owner Instead of Building a Proper Business System
Many Nigerian small businesses are built around one individual.
The owner finds customers, purchases stock, supervises employees, handles payments, manages social media, negotiates with suppliers and resolves virtually every operational problem.
At the beginning, this arrangement may work.
As the business grows, it becomes a serious limitation.
Employees cannot make decisions without the owner’s approval. Customers experience delays when the owner is unavailable. Financial transactions become difficult to track. Important business information remains in the owner’s head rather than being documented.
This creates a business that may generate income but cannot operate independently.
Weak internal controls also increase the risk of theft, fraud, poor customer service and avoidable operational losses.
Compliance is another area that small businesses cannot afford to neglect.
Nigeria’s new tax framework took effect on 1 January 2026. Under the Nigeria Tax Act 2025, a small company is defined as one with annual gross turnover of no more than ₦50 million and total fixed assets not exceeding ₦250 million. Businesses providing professional services are excluded from that definition.
The Act provides for a zero per cent company income tax rate for qualifying small companies. This should not be interpreted as a blanket exemption from every other tax or statutory obligation.
The Nigeria Tax Administration Act 2025 also requires persons and businesses, including companies exempt from income tax, to maintain adequate accounting records. Section 31 requires these records to be retained for at least six years after the relevant year of assessment.
Small businesses that ignore documentation, employment obligations, contractual responsibilities and applicable tax requirements can expose themselves to unnecessary financial and legal risks.
How to avoid this mistake
Entrepreneurs must move from running a personal hustle to managing an organised business.
Start by documenting the essential processes involved in running the enterprise.
Establish clear procedures for purchasing, sales, inventory, customer complaints, payments and record-keeping.
Employees should understand their responsibilities and the limits of their authority.
Introduce simple controls, including regular stock checks, approval procedures for significant expenses, daily sales reconciliation and separation of duties where the size of the business permits.
Digital tools can also improve efficiency. Customer relationship management systems, inventory applications, accounting software and online payment platforms can reduce manual work and improve access to business information.
Owners should regularly review their tax obligations and seek professional guidance where necessary. They should also maintain important business documents, including contracts, invoices, receipts, payroll records and statutory filings.
Finally, build a business that can function when the owner is away.
The objective is not to remove the entrepreneur from the business. It is to ensure that the business does not stop functioning whenever the entrepreneur is unavailable.
The Real Difference Between a Struggling Business and a Sustainable One
Nigeria’s business environment is challenging, and no amount of planning can completely eliminate the consequences of poor electricity supply, insecurity, inflation or expensive credit.
Yet businesses can improve their chances of survival by making better decisions about customers, finances, capital, pricing and management.
The five problems are also connected. Poor market research leads to weak sales. Weak sales expose cash-flow problems. Poor financial records make accessing credit more difficult. Underfunding limits operational efficiency, while weak management systems make it harder to adapt.
The solution is to treat business management as a continuous process rather than something that only matters when problems emerge.
A small business owner should know how much money the enterprise makes, how much it spends, which products generate the strongest margins, who its most valuable customers are and how long it can survive if sales suddenly decline.
These questions are more important than the appearance of success.
For Nigerian entrepreneurs, the goal should not simply be to start another business or generate more daily sales. It should be to build an enterprise that earns consistently, manages its risks, retains customers and remains capable of operating when economic conditions become difficult.
A business does not become successful because it opens its doors. It becomes successful when it can keep them open without constantly depending on luck.
Follow us on our broadcast channels today!
- WhatsApp: https://whatsapp.com/channel/0029VawZ8TbDDmFT1a1Syg46
- Telegram: https://t.me/atlanticpostchannel
- Facebook: https://www.messenger.com/channel/atlanticpostng
Join the debate; let’s know your opinion.