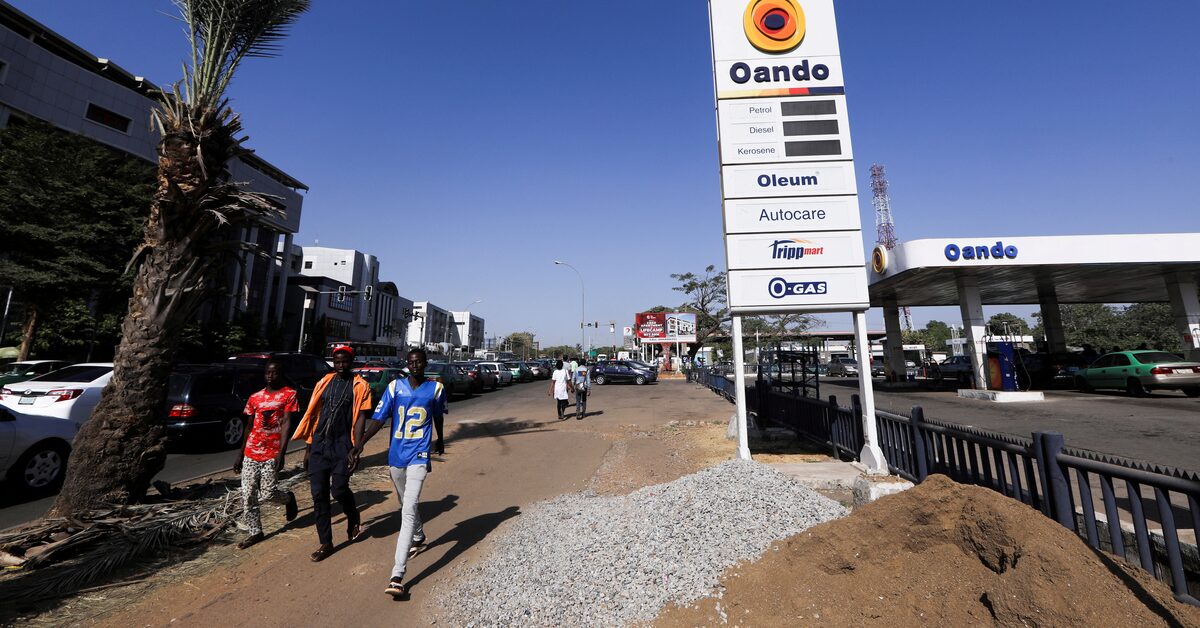
Petrol imports leapt 47% in October 2026, to 15 million litres per day, even as domestic refinery output climbed to 31.9m L/day. In effect, nearly a third of Nigeria’s fuel “receipts” still came from abroad. This surprising rebound, after months of shrinking imports, exposes a basic fact: growing capacity alone has not cured Nigeria’s fuel supply woes.
Our investigation shows that even with Dangote’s mega-refinery running flat out, a combination of exports, infrastructure gaps and market forces has kept the tap of foreign fuel open. The result is a still-fragile supply chain and dangerously thin buffers: petrol stock cover in October fell to just 21.8 days, well below the 30-day safe level.
The NMDPRA October 2026 fact sheet (released 20 Nov) confirms the data. It shows total daily fuel receipts up 21% to 46.9m L/day (from 38.7m in Sept). Of the 8.2m L/day increase, 4.8m came from imports and 3.4m from local refineries.
In percentage terms, imported petrol rose from 26.4% to about 32% of all supply. By contrast, domestic supply, which is largely Dangote’s output, grew only 12% (from 28.5m to 31.9m). In other words, exports and imports outpaced gains from local refining.
The NMDPRA defines receipts as “volumes received into depots, including products trucked directly from refineries,” whereas consumption is fuel trucked into the market. In October, “consumption” was ~46.5m L/day (up 5%), roughly equalling supply.
But stockpiles sagged. Fuel cover slid to 21.8 days in October (down from 23.9 in September), far below the regulator’s 30-day benchmark. Inland depots held just 19.5 days and offshore tanks 2.3 days. In short, Nigerians were burning through stock faster than it could be replenished.
Dangote’s role, and exports
Domestic output gains have been driven almost entirely by the Dangote refinery. (Government refineries in Port Harcourt, Warri and Kaduna remain offline.) Dangote’s facility ran above 100% of its nameplate capacity in October: NMDPRA data show it was operating at 103.7% of 650,000 bpd. Its daily petrol production averaged 48.51m L. Of that, only 31.89m L were sold locally; 20.18m L (42%) was exported.
In other words, even with Dangote maxed out, nearly half its petrol went overseas. The refinery also drew on 3.56m L from stocks to meet demand, and its own closing inventory plunged 37% to 229.9m L.
The implication is stark: Nigeria’s largest refinery is feeding export markets and drawing down inventory, leaving domestic consumers partially reliant on imports. Indeed, Dangote has struck deals to supply neighbouring markets (Botswana, Cameroon), further diverting product.
Meanwhile, old modular refineries contribute only a trickle (about 680,000 L/day of diesel from small plants). In sum, most petrol consumed is refined in Nigeria only on paper as much of the gasoline is made domestically but ends up abroad. As the regulator notes, this helps “reduced reliance on imports” on net, yet it also means domestic demand still needs backup from foreign supply.
The month-by-month series underlines the volatility. At the 2025 year-end, imports still dominated: Dec 2025 saw 42.2m L/day of imports vs 32.0m from local refineries. But in early 2026, Dangote’s ramp-up flipped the pattern: January’s 40.1m L domestic vs 24.8m import, and a historic trough in Feb when imports fell to just 3.0m L/day.
As stock buffers ran low, imports later began to rebound: they jumped sharply in June–July (to ~18–19m L/day) as domestic deliveries dipped, and now ticked up again in October. The data show imports still below the 13-month average (~18.8m), but creeping back towards it.
Fragile economy and supply chain
Why the sudden surges in imports even as refining capacity improves? Partly it’s economics. Although Nigeria removed most fuel subsidies this year, pump prices remain uniform and much lower than black-market cross-border rates. That artificially high local demand (93% of a 50m L/day benchmark) creates an incentive for smuggling or arbitration, which fuels shortages.
Abroad, global oil prices have been volatile (Brent averaged $125/bbl in Oct) but the naira’s slide also makes imports costly. Still, regulators report marketers cutting retail prices in late Oct as crude prices eased, suggesting some importers did bring cheaper fuel.
In short, complex market signals are at play, with foreign-supplied fuel remaining an attractive source when local systems falter.
Infrastructure is another key issue. The domestic supply chain (pipelines, depots and trucks) was not built for this new scale. Bottlenecks mean even Nigeria’s own petrol may not reach consumers efficiently. Last-mile logistics shortfalls force many marketers to top up stocks via imports through seaports.
Indeed, with onshore and offshore stocks only covering 21.8 days, any pipeline or plant downtime can trigger urgent imports. There’s also a credit crunch: oil companies face high local interest rates and dollar shortages, sometimes resorting to syndicated fuel imports financed by crude swaps or petrol-for-crude deals. These factors can prompt a jump in imports whenever domestic output dips or demand spikes, as in October.
Exports vs. the home market
Crucially, Dangote’s export-oriented strategy means local supply is not automatically recycled at home. Over October, Dangote’s combined exports (petrol, diesel, aviation fuel) averaged 55.28m L/day against 43.96m L/day sent into the Nigerian market. A crude equation emerges: Nigeria produces more than it uses, but sends a chunk overseas.
Fuel marketers have historically relied on imports to arbitrage between FX markets or hedge against domestic shortfalls. In October, with Dangote selling fuels to buyers abroad and local depots running lean, importers had to step in.
This pattern underscores a broader truth: boosting local refining capacity is necessary but not sufficient. Nigeria still lacks control over where that fuel ends up. As the NMDPRA dryly notes, the recovery in refining “has not completely eliminated the need for imported petroleum products”. That sentence is a diplomatic understatement: domestic production has risen 86.5% year‑on‑year, while imports fell 48.1%, yet imports are creeping back.
The October rebound was “accompanied by deterioration in petrol stock sufficiency”; precisely because the supply chain relies on imports for resilience.
Outlook: building a resilient system
NMDPRA’s October report (and its January–Oct summary) is a reality check. It shows crude receipts to refineries up 19%, yet still only 144.98m of 179.31m barrels (80.9%) came from local oil. Imported crude (to Dangote) rose 39%, reflecting global sourcing. The three state-owned refineries remain sidelined, meaning the country’s fate rests on one private complex and a handful of small modular plants.
Until Nigeria develops alternate refining capacity or upgrades distribution, any hiccup, whether a pipeline leak (FX crunch or sudden demand surge) could necessitate more imports. Policymakers must tackle this latent vulnerability. That means not only keeping refineries running (plans to revive Warri/Kaduna have been slow to materialize), but also investing in storage, pipelines and smarter pricing.
Increased transparency in stock levels and market allocations could also help avoid panic buying. And with Dangote’s own expansion (recently doubled to 700,000 bpd), there’s hope of eventual surplus.
But for now, Nigeria’s journey to fuel independence remains incomplete. As one analyst wryly notes, “supply is not yet fully local; so global prices and the naira still affect what you pay at the pump”.
Follow us on our broadcast channels today!
- WhatsApp: https://whatsapp.com/channel/0029VawZ8TbDDmFT1a1Syg46
- Telegram: https://t.me/atlanticpostchannel
- Facebook: https://www.messenger.com/channel/atlanticpostng
Join the debate; let’s know your opinion.